 By
Why Smarter Payments Matter More Than Ever
As digital payments become part of everyday life, seamless payment options are helping Kenyans save time, improve security and manage their finances more efficiently.
For many Kenyans, paying for everyday needs has become a series of quick digital transactions.
From buying groceries and paying school fees to settling utility bills, purchasing fuel or sending money to family, consumers are constantly looking for faster and simpler ways to pay.
The shift is happening as Kenya’s digital payments ecosystem continues to expand. Central Bank of Kenya data shows that registered mobile money accounts reached 94.35 million in July 2026.
As a result, convenience, reliability and security are becoming basic expectations.
Digital payments also create value beyond convenience. For business owners, faster transactions can save time and reduce the need to handle cash.
Digital records can also make it easier to track payments and manage business finances. At the same time, reduced cash handling can lower some of the risks that come with carrying physical money.
For consumers, seamless payments mean fewer steps at the point of purchase. Instead of moving money between different platforms before paying a bill, customers can increasingly complete transactions directly from their preferred banking or payment platform.
Kenya’s Digital Payments Journey
Kenya has built a strong reputation for mobile money innovation. The Central Bank of Kenya notes that mobile financial services have expanded access to financial services and helped put the country on the global payments map.
The growth has also changed how Kenyans interact with businesses.
Digital payments allow customers to transact without carrying large amounts of cash. They can also provide transaction records, which can support better money management.
The wider financial inclusion impact is significant. CBK’s 2024 FinAccess findings showed that access to formal financial services and products reached 84.8% in 2024. Mobile money remained a key driver of financial inclusion.
However, the growth of digital payments also raises an important question: are consumers making the smartest choices with the tools available to them?
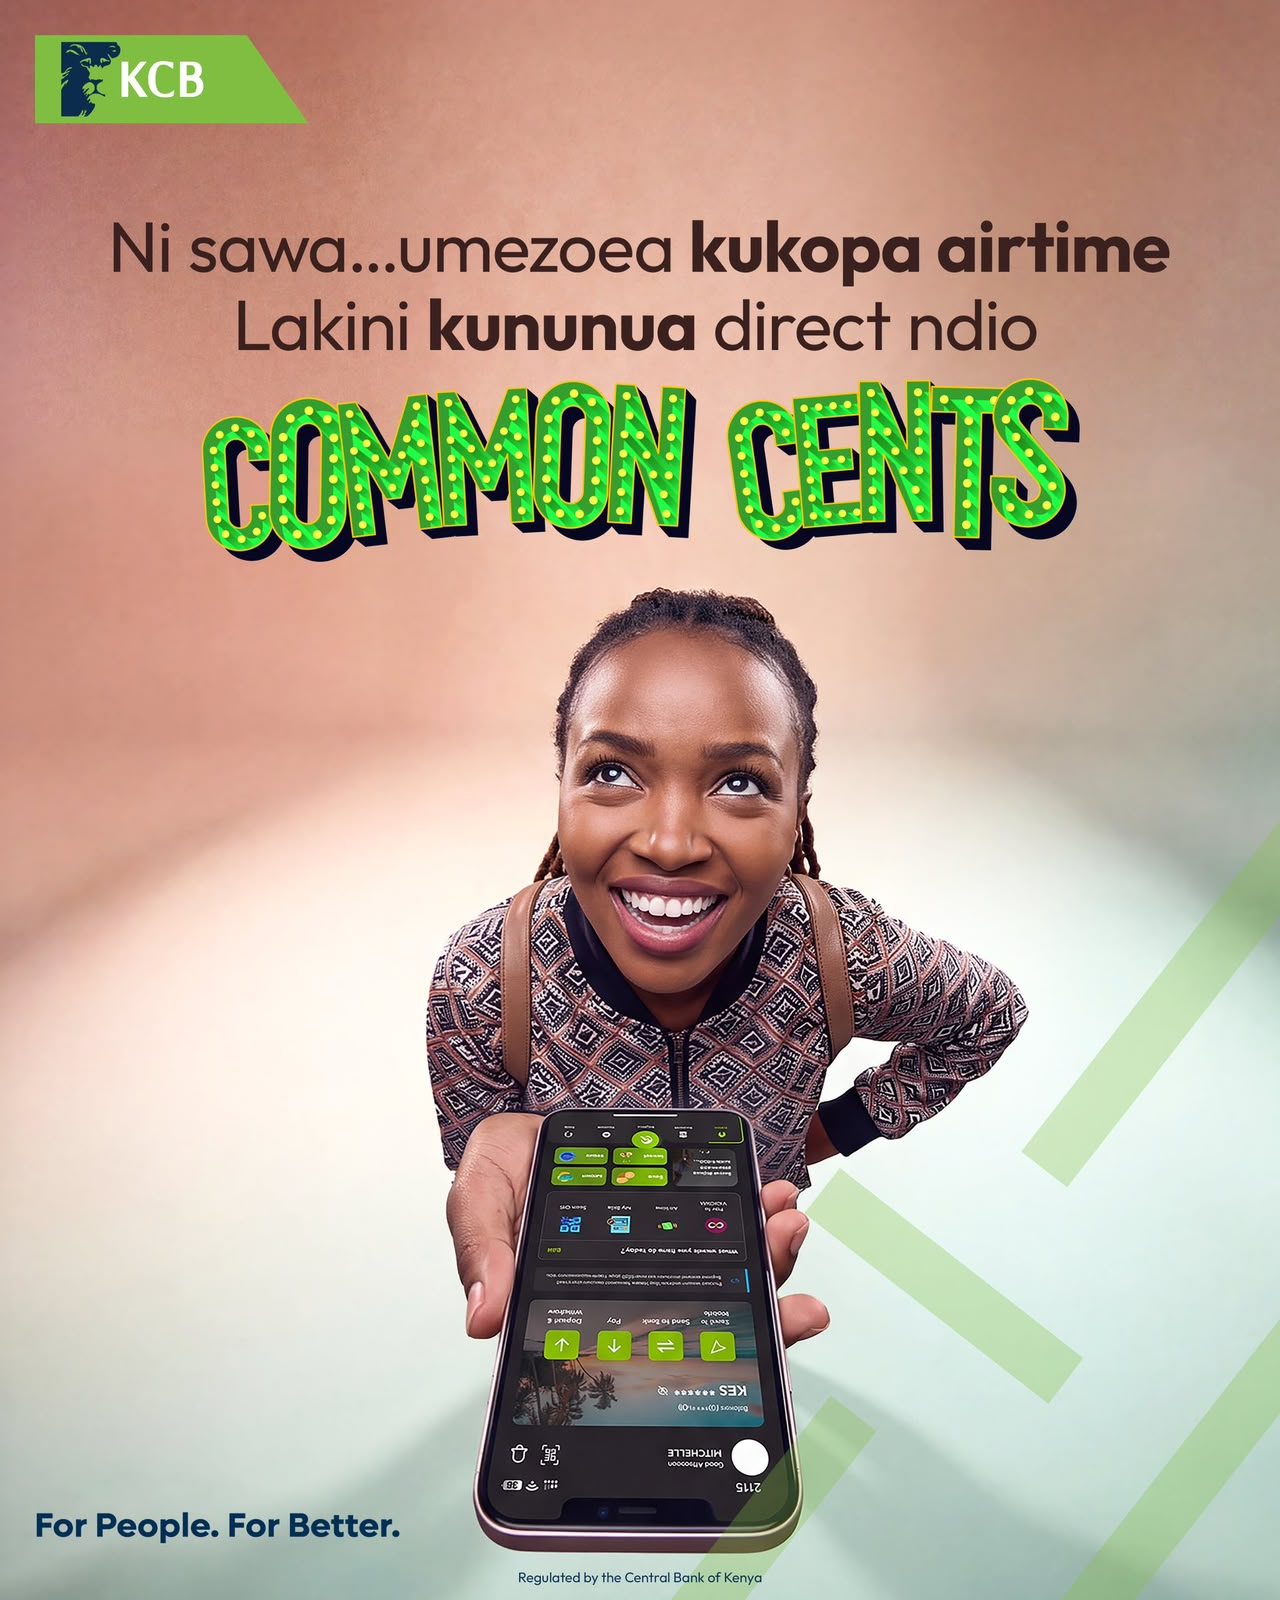
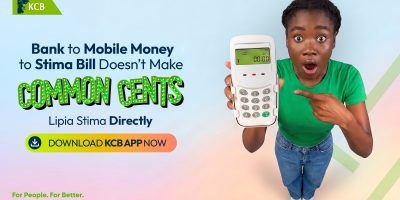
That is where the idea of “Common Cents” comes in.
Making a payment smarter is not only about completing a transaction. It can also mean choosing an option that saves time, reduces unnecessary steps and makes it easier to keep track of your money.
Bringing More Payments Into One Place
The KCB Mobile App provides customers with several payment options from a single platform.
Customers can pay KPLC tokens, school fees, eCitizen and government services, water bills and other everyday expenses directly from their accounts. The app also supports Lipa na KCB merchant payments.
This approach reduces the need to move money from one platform to another before completing a payment.
For businesses, digital payment tools can also support more efficient collection and financial management. KCB provides digital payment solutions for areas such as school fees, bills and statutory payments.
The bigger opportunity lies in making digital payments work around the realities of everyday life.
A business owner can spend less time handling cash. A parent can settle school fees from their phone. A customer can pay a utility bill without making several separate transactions.
Why Smarter Payments Matter More Than Ever
Making Every Payment Count
The evolution of digital payments is ultimately about more than technology.
It is about giving people simpler ways to manage their money and participate in an increasingly digital economy.
For consumers and businesses alike, smarter payment choices can mean fewer steps, better records and more time for other priorities.
In a country where digital payments continue to grow, making every transaction count could be one of the simplest ways to practise good financial sense.
Because sometimes, Common Cents is simply choosing the smarter way to pay.
More rerated reads are here








Comments