 By
Financial Inclusion Is Evolving: Why Access Alone Is No Longer Enough
As more Kenyans enter the formal financial system, the next challenge is helping people use financial services to build resilience, manage money and grow.
For years, financial inclusion in Kenya was largely about one question: can people access financial services?
Today, that question is changing.
A bank account, mobile wallet or access to credit can open a door. However, true financial inclusion goes further. It asks whether people can use those services to manage daily needs, withstand financial shocks, save for the future and grow their businesses.
That shift is becoming increasingly important as technology changes how Kenyans interact with financial institutions.
According to the 2024 FinAccess Household Survey, access to formal financial services reached 84.8% in 2024, up from 83.7% in 2021. Mobile money remains a major driver of this progress.
Yet, access does not automatically translate into financial wellbeing.
The Central Bank of Kenya’s Financial Sector Stability Report notes that only 18.3% of adults were financially healthy in 2024. The report links the decline to factors including rising indebtedness, low financial literacy and limited ability to absorb financial shocks.
This is where the next chapter of financial inclusion begins.
From Access to Financial Wellbeing
The distinction is easy to understand.
Someone may have access to a mobile wallet but still struggle to manage monthly expenses. A small business may accept digital payments but lack the tools to manage cash flow.
Likewise, a customer may access credit but still struggle to build savings or prepare for an unexpected expense.
The challenge, therefore, is not simply bringing more people into the financial system.
It is making that system work better for the people already using it.
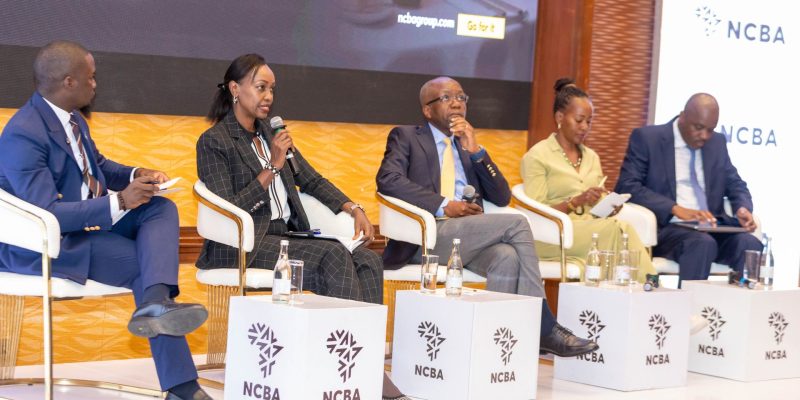
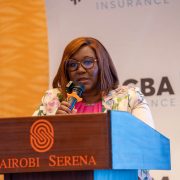
This was one of the central ideas behind NCBA’s “Beyond Banking: Shaping the Future of Inclusive Finance” forum.
The forum brought together leaders from banking, fintech, SACCOs and microfinance to examine how technology and collaboration can shape the next phase of financial inclusion.
Why No Institution Can Do It Alone
Financial services have traditionally operated across different institutions.
Banks bring capital, technology, payment infrastructure and risk management. SACCOs and MFIs, meanwhile, often have deep relationships with communities and a strong understanding of their members.
Fintechs add another layer through technology, data and new ways of solving customer problems.
Wangaruro Mbira, CEO of MyCredit Microfinance and Chairman of AMFI Kenya, argued that these strengths should work together.
He said the future will depend less on institutions working in isolation and more on a connected financial ecosystem.
That could change how financial products are designed and delivered.
For example, a bank can provide infrastructure and capital. A SACCO can bring its understanding of members. A fintech can add technology that makes the service easier to access.
Together, these capabilities can address needs that one institution may struggle to meet alone.
Technology Must Solve Real Problems
Digital transformation has already changed how Kenyans make payments, access credit and manage their accounts.
However, technology is most useful when it solves a problem that customers actually face.
For a small trader, that could mean receiving payments quickly and keeping better records.
For a SACCO member, it could mean accessing services without losing the personal connection that built trust.
For a growing business, it could mean using transaction data to understand cash flow and make better financial decisions.
The NCBA forum highlighted digital banking, cybersecurity, responsible digital lending and embedded finance as some of the issues shaping the future of financial services.
The conversation is therefore moving beyond simply putting financial services online.
It is about making those services useful, safe and relevant.
Building Trust in a Digital Financial System
Greater digital adoption also brings new responsibilities.
As more customers transact online, financial institutions must pay attention to cybersecurity, consumer protection and responsible lending.
This is particularly important as digital credit becomes easier to access.
Convenience should not come at the expense of financial wellbeing. Instead, technology should help customers make informed decisions and understand the financial products they use.
The Kenya National Financial Inclusion Strategy 2025–2028 also highlights gaps in product usage, financial literacy and affordability despite the country’s high level of financial access.
That makes trust a critical part of the next phase.
Customers need confidence that their money and data are protected. They also need products that match their circumstances rather than simply making financial services easier to consume.
The Next Frontier Is Financial Health
Kenya has already demonstrated what technology can do for financial access.
Mobile money helped take financial services beyond traditional branches. Digital banking has made transactions faster. Fintechs have introduced new ways for consumers and businesses to access financial products.
Now, the opportunity is to build on that foundation.
Financial inclusion should help people do more than transact.
It should help them manage money better, build resilience, grow businesses and plan for the future.
That will require cooperation across banks, SACCOs, MFIs, fintechs, regulators and technology companies. The NCBA forum brief similarly identifies collaboration across these players as critical to building a more inclusive financial ecosystem.
The future of inclusive finance, therefore, may not belong to one type of institution.
It could belong to the ecosystem that connects their strengths.
And for the customer, the measure of progress may become much simpler: not just whether financial services are available, but whether they actually help people live, work and build with greater financial security.







Comments